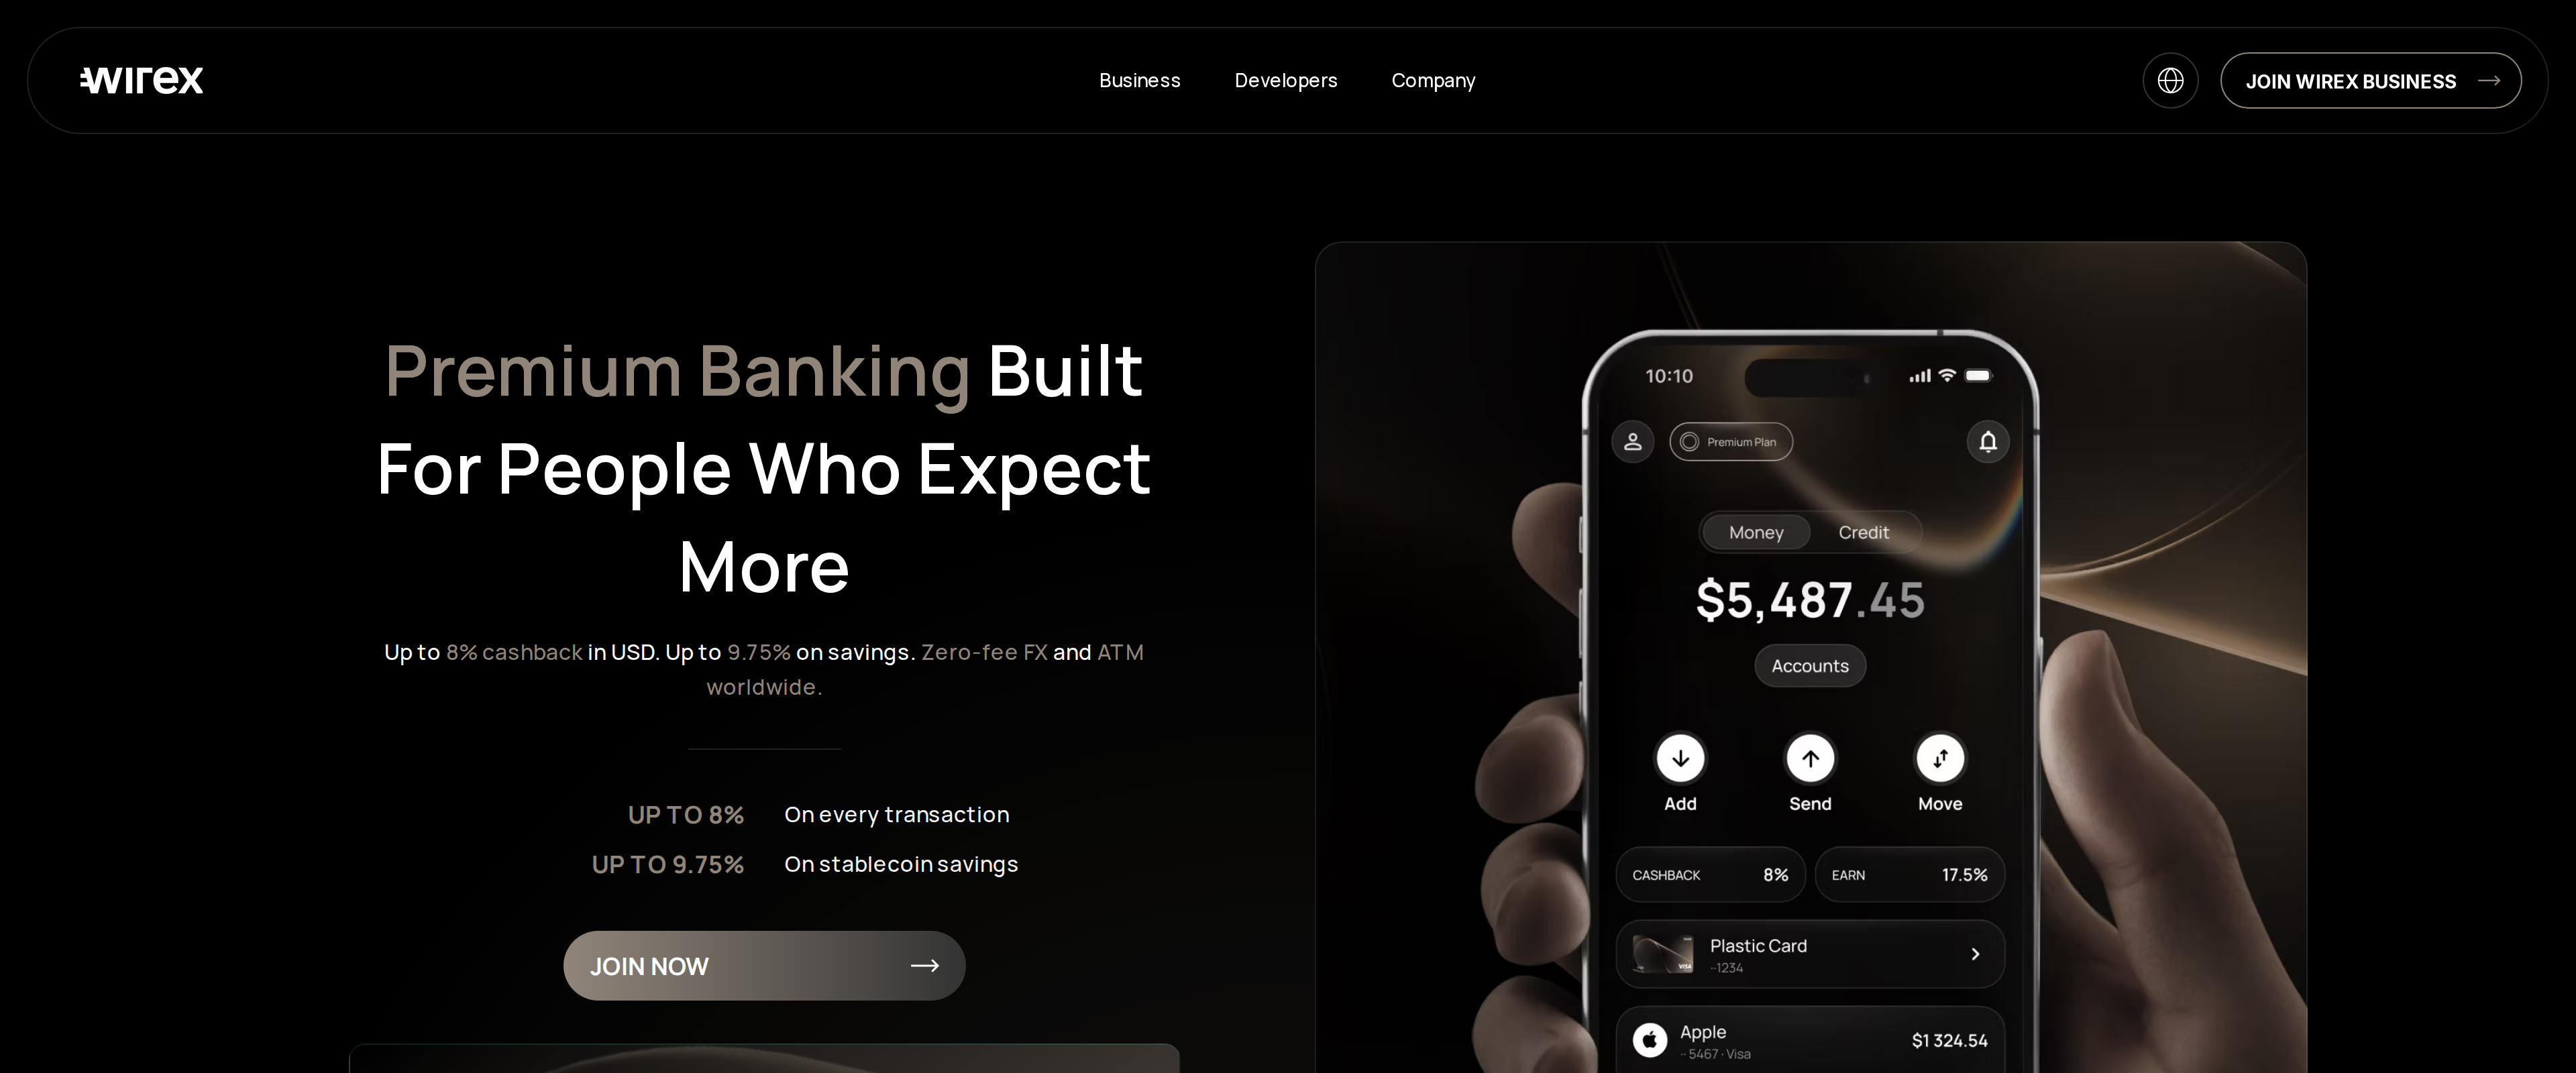
Wirex built its name on a multicurrency card with crypto cashback, then in 2026 started pushing existing users toward a rebuilt product called Wirex One with balance-based tiers instead of a subscription. We tested the spending, the savings rate and the 2022 FCA episode that still shapes how it operates in the UK.
Wirex earned its reputation the ordinary way: a card that lets someone hold crypto and stablecoins, then spend them at a normal merchant terminal without a separate cash-out step. We used ours across three countries over several weeks, and the harder story turned out not to be the spending experience but the fact that Wirex is actively rebuilding itself underneath its long-time customers.
Two products, one brand, right now
Wirex's own blog carries a post addressed directly at its existing base: "Already Got a Wirex App Account and Interested in Joining Wirex One?" That single line tells a reader most of what they need to know before comparing prices anywhere else. Wirex One is a rebuilt product with tiers set by account balance and WPAY holdings rather than a flat monthly subscription, and it is being rolled out alongside, and eventually in place of, the older Wirex App tier structure that most existing reviews online still describe.
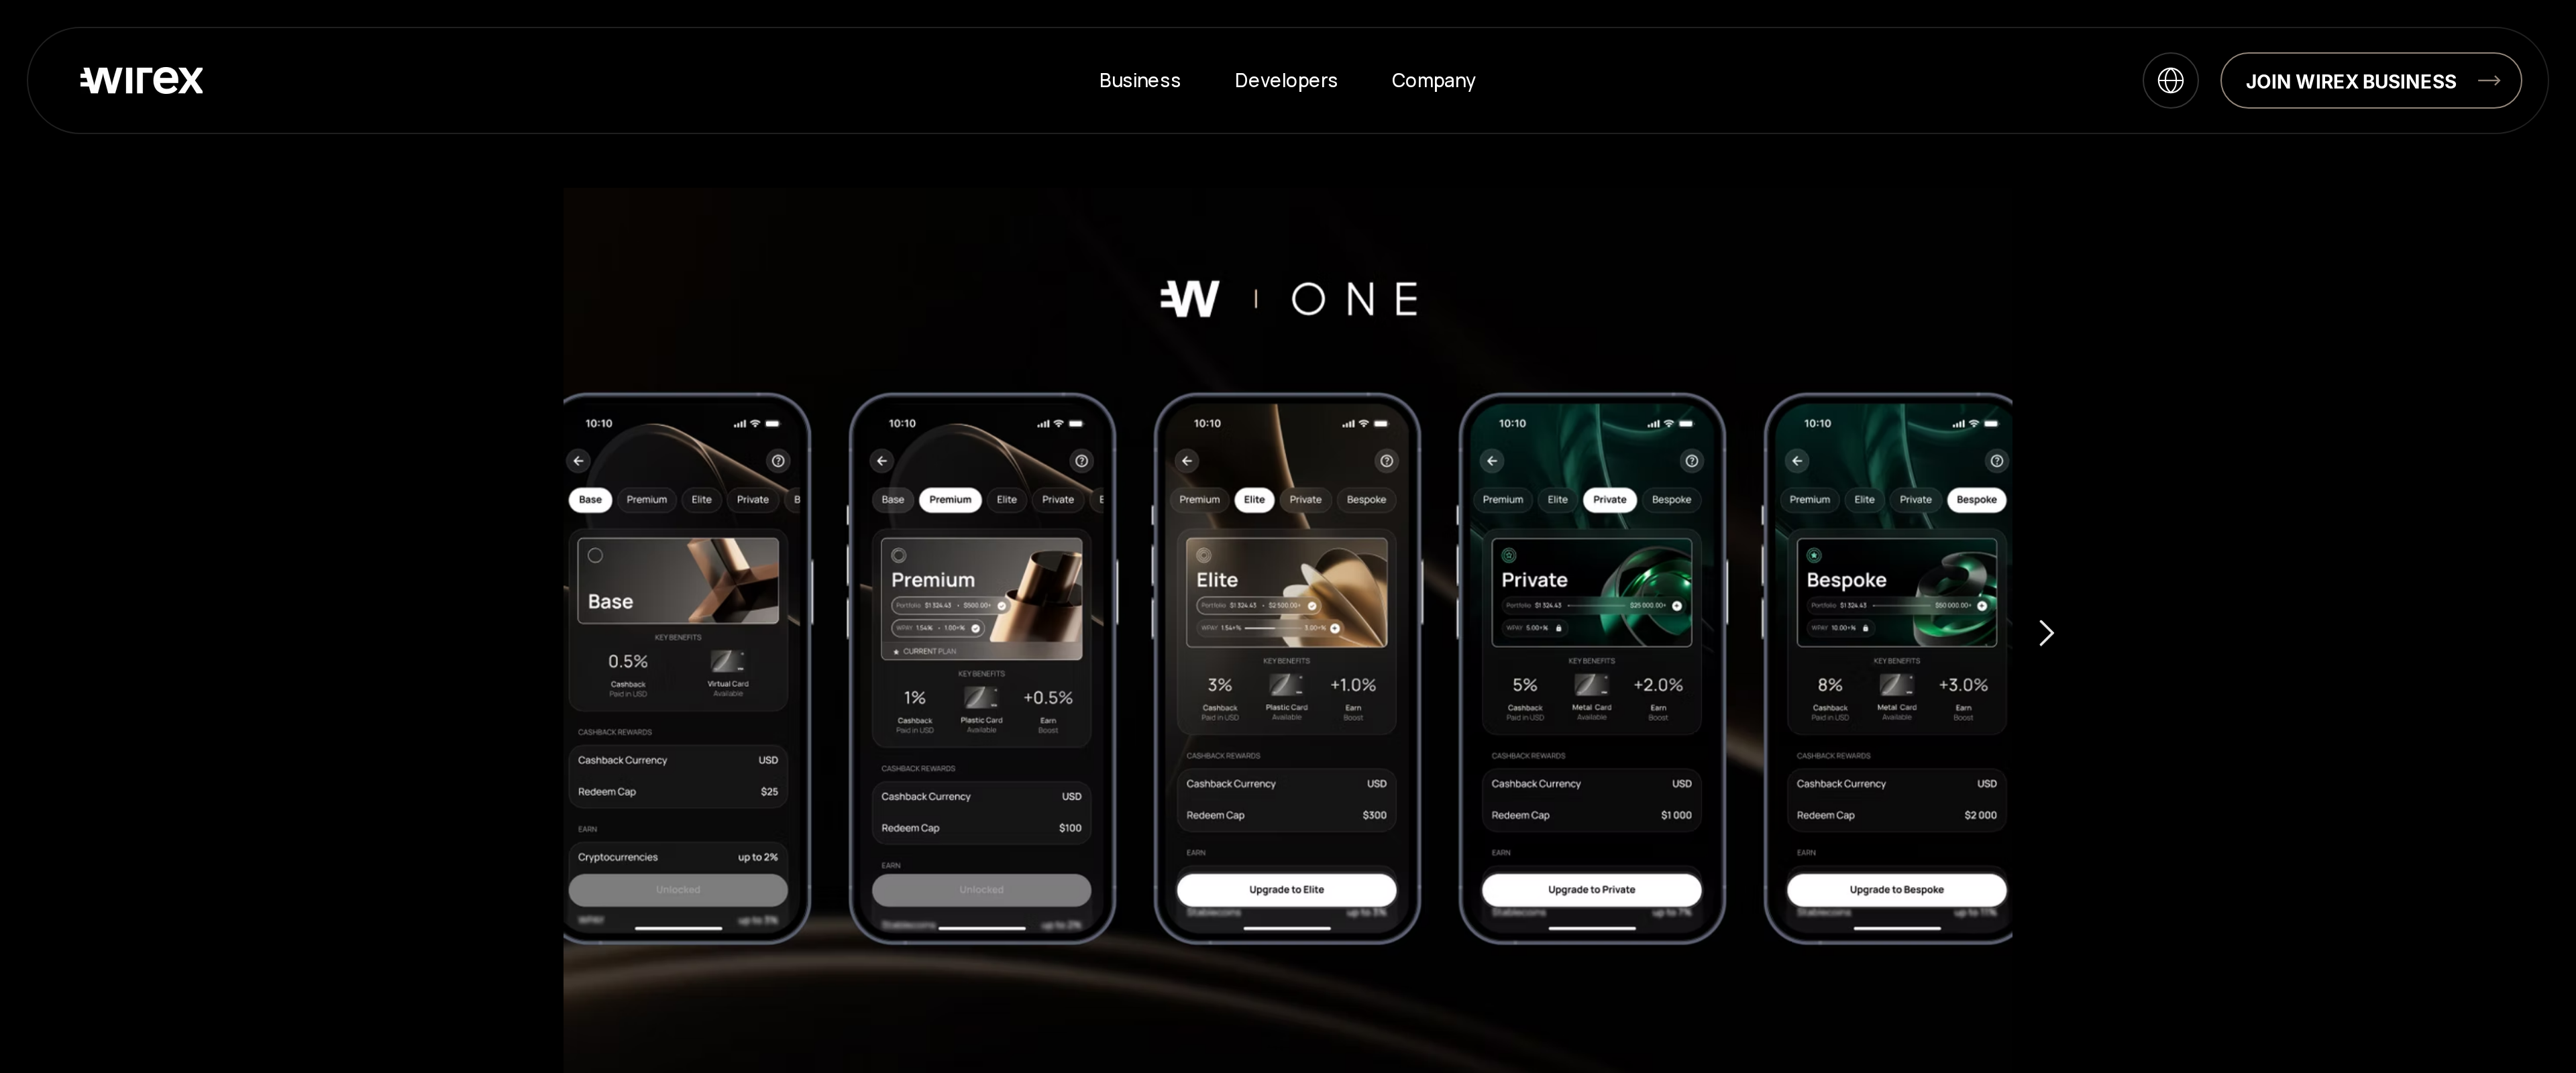
That transition matters for a simple reason: a cashback percentage or a savings rate quoted by an older review may describe a product structure Wirex is phasing out. We checked the live personal product page rather than trusting a cached number, and it currently advertises cashback up to 8% in USD and stablecoin savings up to 9.75% APY, alongside zero-fee foreign exchange and ATM withdrawals worldwide for qualifying tiers.