Crypto CardsReview
Nexo Card Review: Real Cashback, Locked Behind Loyalty Tiers
We tested the Nexo Card's switch between Debit and Credit mode and worked through its Loyalty tier requirements to see whether the advertised 2% cashback survives contact with the $5,000 balance and NEXO token conditions attached to it.
Our verdict
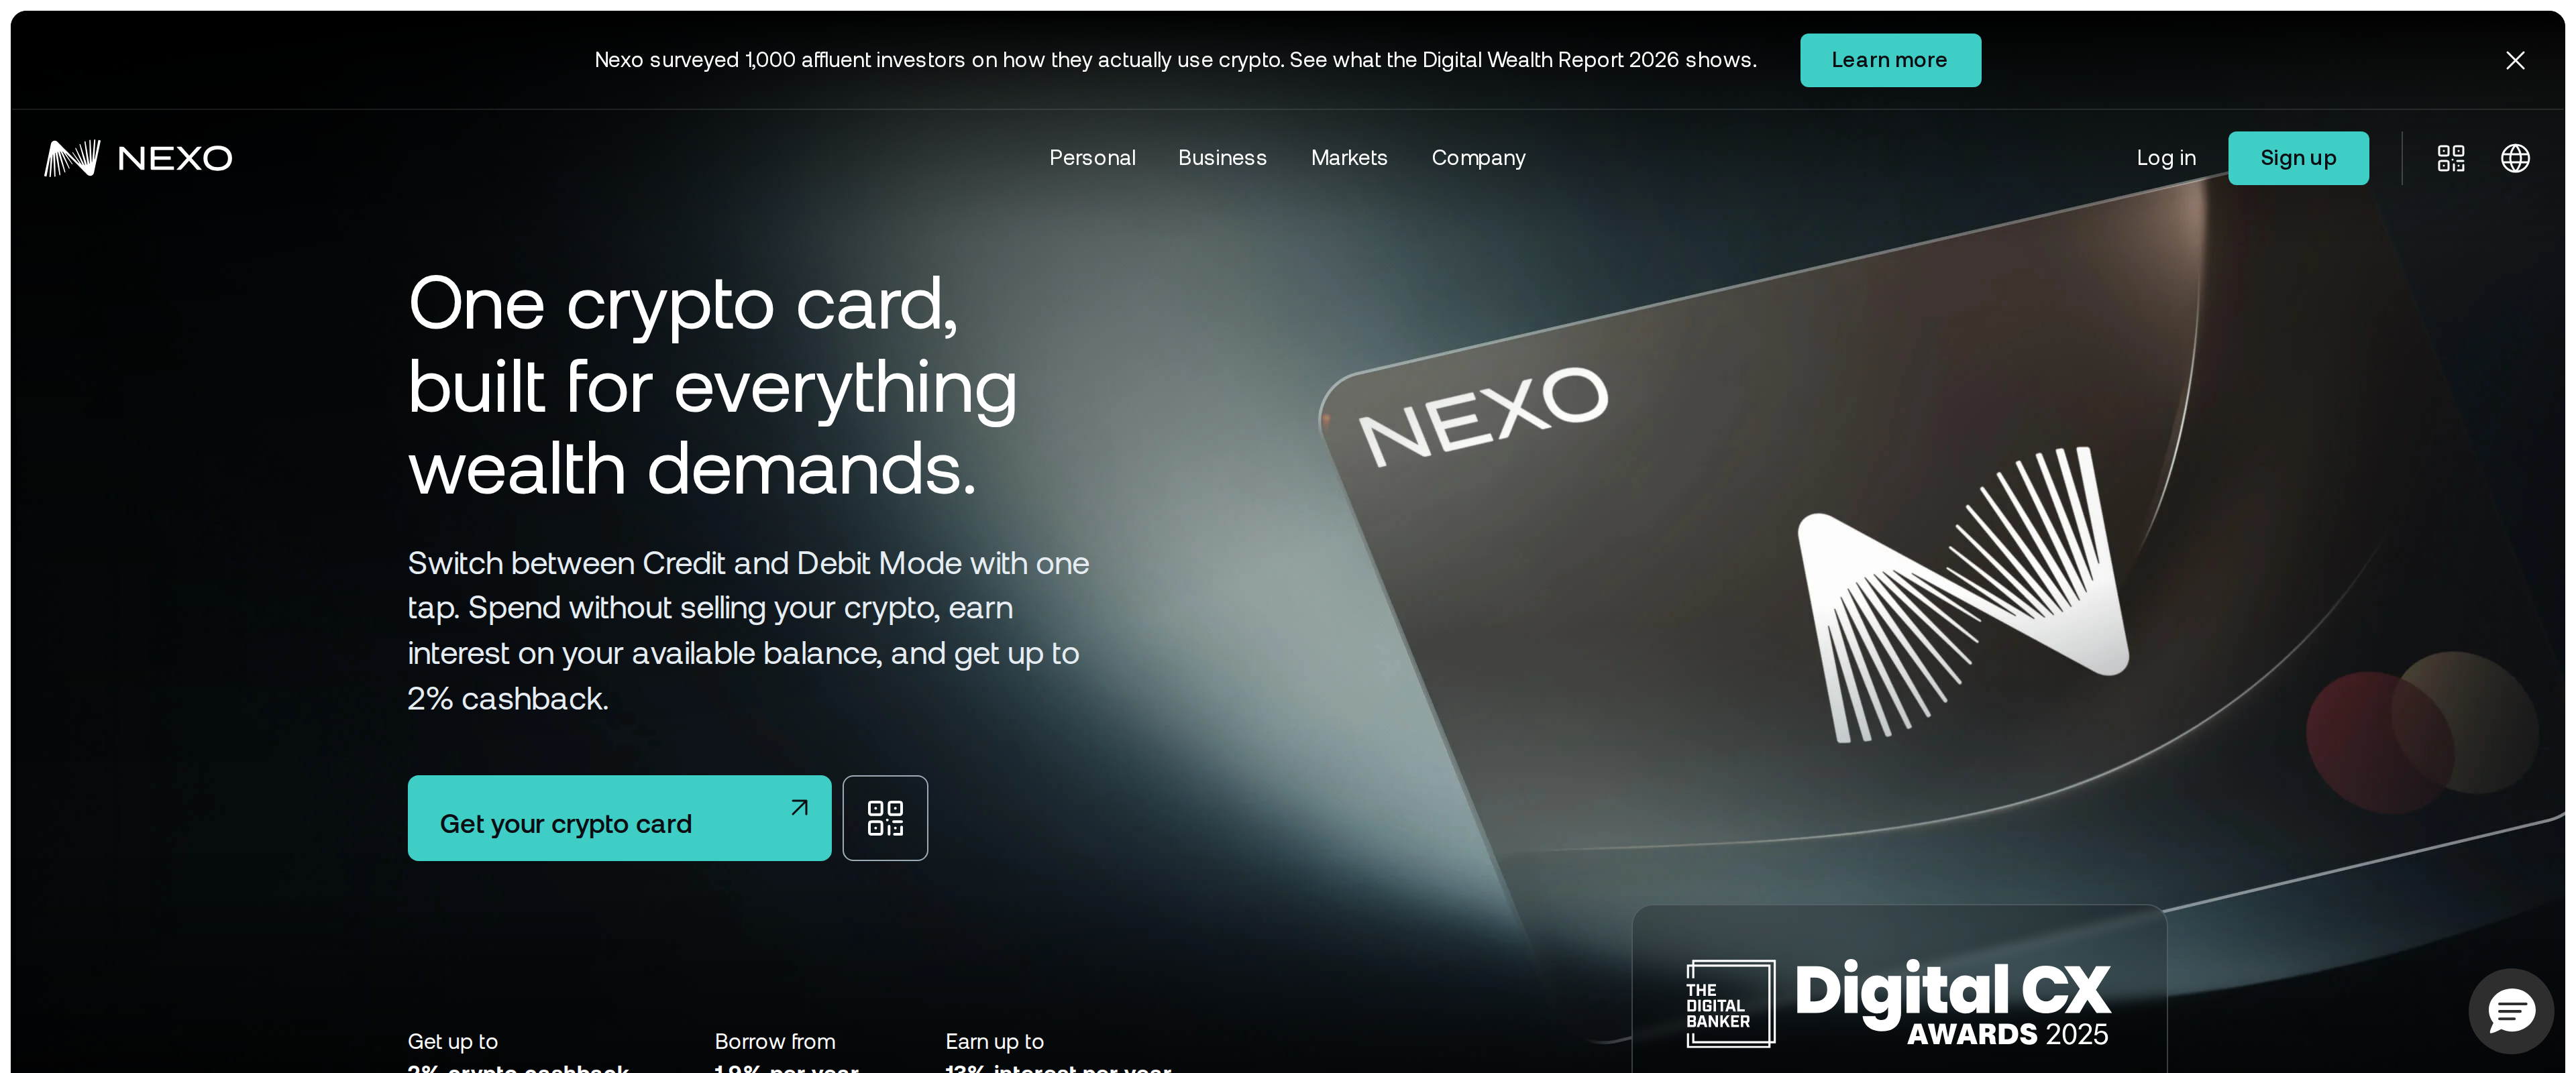
The Nexo Card genuinely does what it says: switch between spending your balance and borrowing against it with one tap, at no monthly fee. But the advertised 2% cashback needs Platinum status and a $5,000-plus balance, and it is only available in the EEA, the UK and a handful of nearby countries, so most of what makes it interesting only shows up once you already have real money parked with Nexo.
Best for: Existing Nexo users in Europe with a balance above $5,000 who want to spend or borrow without selling their crypto
- Price
- No monthly or annual fee
- Made by
- Nexo
What we liked
- No monthly, annual or inactivity fees on the card itself
- One-tap switch between Debit mode and Credit mode, so spending doesn't force a sale
- Credit mode borrowing starts from 1.9% a year for top-tier holders, with no credit checks
- Virtual card activates instantly with just a $50 minimum balance
What held it back
- Cashback requires a $5,000-plus balance, and the full 2% needs Platinum Loyalty status
- Physical card requires $5,000-plus balance and Gold tier, not just the $50 virtual minimum
- Foreign exchange fees reach up to 2.5% on international weekend transactions
- Only available to residents of the EEA, UK, Switzerland and Andorra, not the US or most of the world
We applied for a Nexo Card using a European test account, funded it past the thresholds the loyalty program cares about, and used it for a mix of everyday purchases and one deliberate test of the borrowing side. The card's whole pitch rests on switching between spending your own balance and borrowing against it, so that was the first thing we checked.
Debit and Credit mode, switched with one tap
In Debit mode, the card spends directly from your stablecoin or crypto balance, converting automatically at the point of sale, and you can drag assets into a priority order so it spends the coin you want first. Flip to Credit mode and the same card instead draws on a credit line secured by your portfolio, so you keep your underlying crypto rather than selling it to cover a purchase. Nexo advertises this as a single tap in the app, and in our test it was: no card reissue, no waiting period, just a toggle that changed which balance the next transaction pulled from.
That flexibility is the card's real feature. Most crypto debit cards only spend a balance; combining it with an on-demand credit line against the same collateral, with no separate credit check, is a genuinely different product from a normal prepaid crypto card.
The 2% cashback headline, and the balance it actually needs
Nexo markets "up to 2% cashback," and that number is real, but it only applies to Platinum Loyalty tier holders, the top of a four-tier system (Base, Silver, Gold, Platinum) that requires holding NEXO tokens equal to at least 10% of your portfolio balance for Platinum, on top of a minimum $5,000 total balance for cashback to activate at all. Drop down the tiers and the cashback drops with it: Gold pays 1% in NEXO or 0.3% in BTC, Silver 0.7% or 0.2%, and Base tier, which is what you get by default without holding NEXO tokens, pays a much thinner 0.5% in NEXO or 0.1% in BTC.
We would call the "up to 2%" framing technically accurate and practically misleading for a new user. Reaching it means holding a meaningful chunk of your balance in Nexo's own token, an extra bet most people did not sign up for when they wanted a debit card.
Borrowing against your crypto instead of selling it
Credit mode's headline rate starts from 1.9% APY, but that figure is also reserved for Platinum members; Base tier borrowers pay up to 18.9%, a gap wide enough to change whether borrowing makes sense at all. There are no credit checks and repayment is flexible, which suits someone who wants short-term liquidity without triggering a taxable sale of their holdings, but a wrong-tier borrower paying 18.9% is not meaningfully better off than a high-interest credit card, and the collateral sits in crypto that can itself lose value while the loan is outstanding.
Specifications
- Price
- No monthly or annual fee
- Card network
- Mastercard, issued by DiPocket UAB
- Top cashback rate
- 2% in NEXO tokens (Platinum tier)
- Credit mode rate
- From 1.9% APY (Platinum), up to 18.9% for Base tier
- Virtual card minimum
- $50 balance
- Physical card requirement
- $5,000+ balance, Gold tier or above
- FX fees
- 0.2% weekday EEA to 2.5% international weekend
- Availability
- EEA, UK, Switzerland, Andorra