Deribit still clears most of the world's Bitcoin and Ethereum options volume. We opened an account, checked the fee caps against real trades, and worked out who the platform actually suits after its move under Coinbase.
Deribit built its name on one thing: options on Bitcoin and Ethereum, priced and matched deeper than anywhere else. We opened an account, ran through the onboarding tiers, and checked the fee math against contracts we actually quoted before deciding who this exchange is really for.
Why options traders end up here anyway
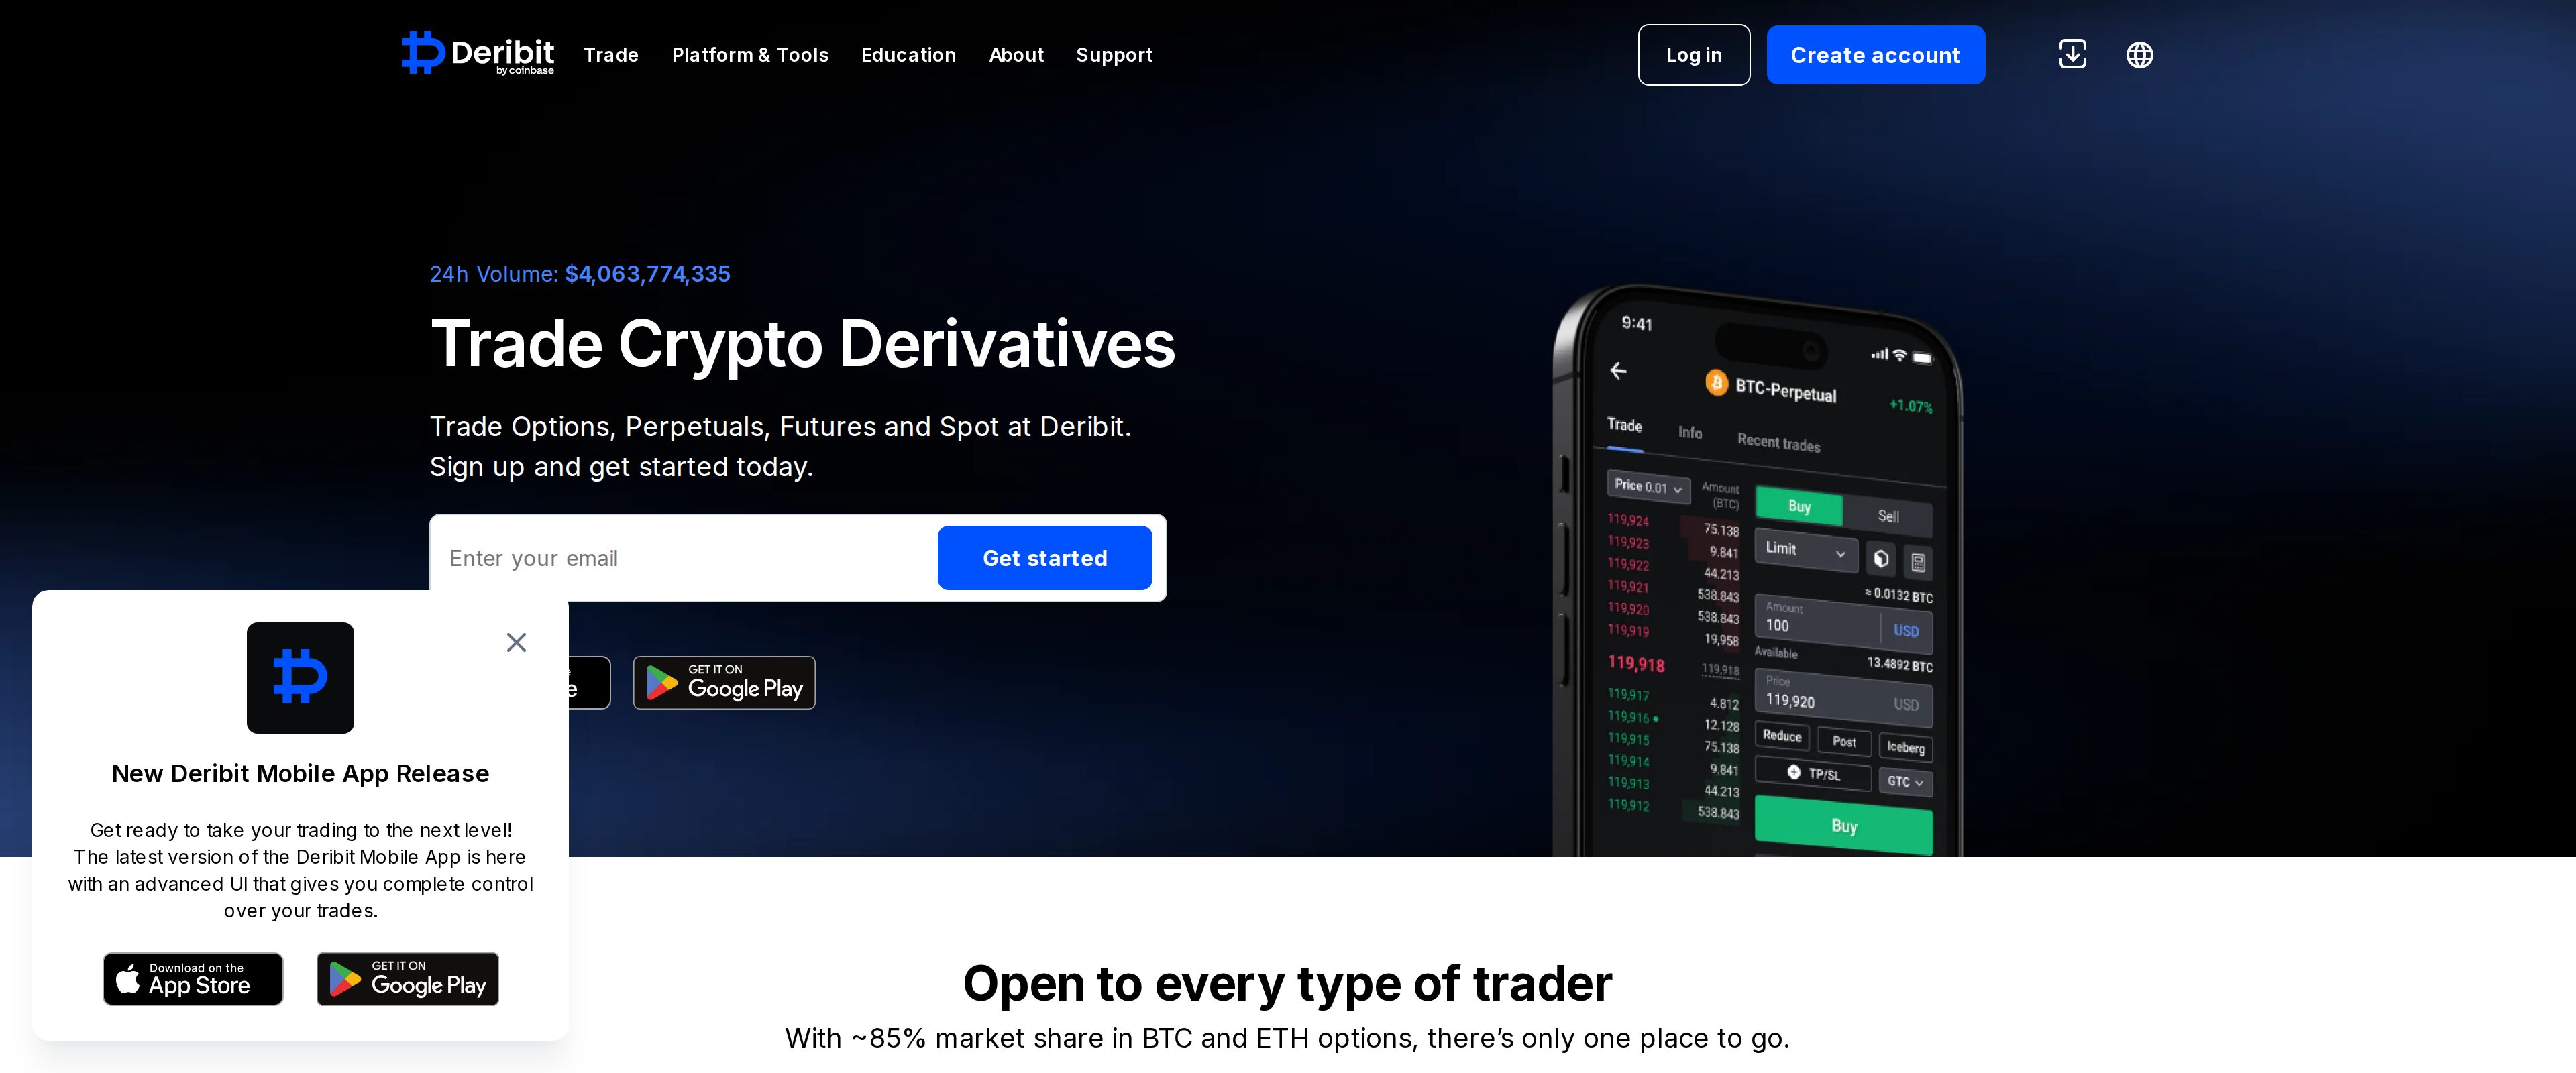
Ask a professional crypto options trader where the liquidity sits and the answer is almost always the same. Deribit reports roughly 85% of global BTC and ETH options volume, a figure that has held for years despite competition from OKX, Binance and newer venues like Delta Exchange. Depth matters more in options than in spot trading because strikes and expiries fragment liquidity across hundreds of separate order books. A thin market on a rival exchange means a wide spread the moment you try to close a position; on Deribit, even strikes far from the current price usually have a market maker quoting both sides.
The platform also covers futures, perpetuals and spot, and folding all four products into one margin account is part of the appeal: a hedged options position and its underlying futures leg net against each other for margin purposes, so capital is not double-counted.
The fee cap that actually matters
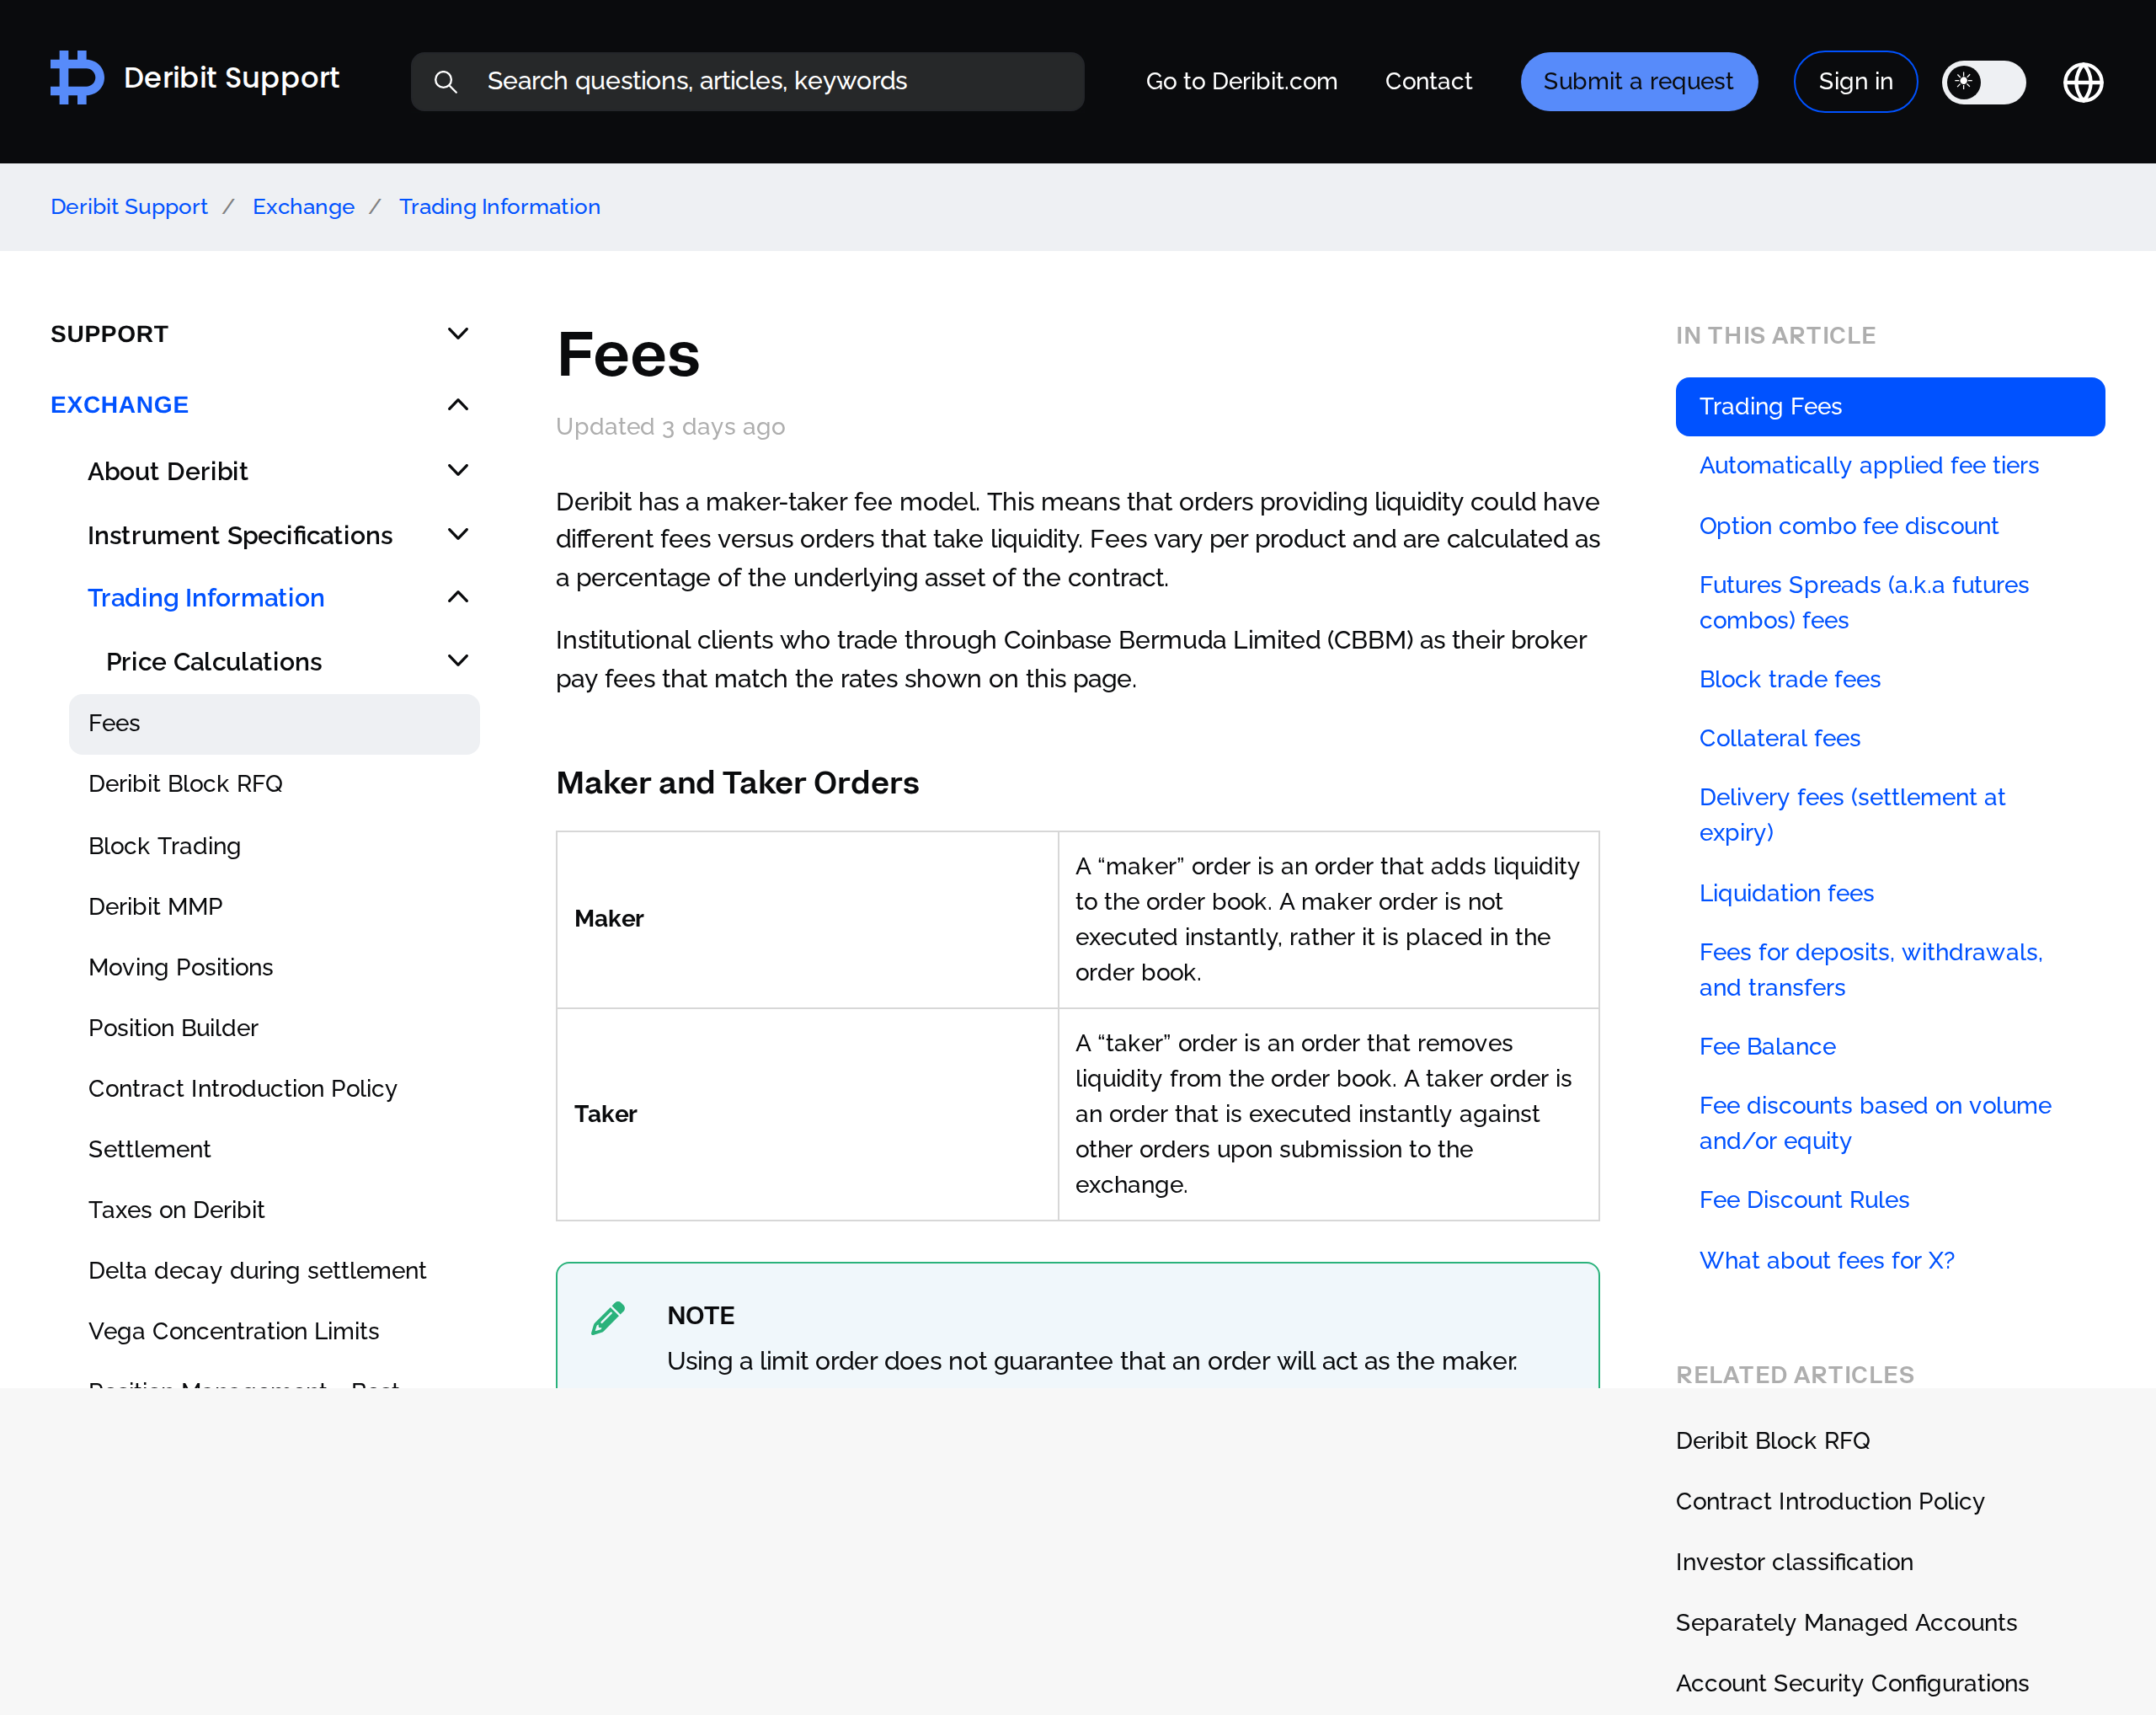
Options pricing on crypto exchanges has a specific failure mode: a deep out-of-the-money contract can carry a tiny premium, so a flat percentage fee on the notional value eats the entire trade. Deribit charges 0.03% of the underlying per contract for both makers and takers, but caps that charge at 12.5% of the option's premium. That cap is the loosest among the venues we compared it against; OKX caps at 7% and Delta Exchange at 3.5%. In practice it means a trader buying cheap tail-risk hedges is not quietly taxed out of the strategy.