AvaTrade review: does AvaProtect earn its wider spread?
AvaTrade sells fixed spreads and a paid loss-insurance feature called AvaProtect instead of the raw pricing newer brokers compete on. We opened a live account, insured a real trade with AvaProtect and checked whether its education centre justifies a EUR/USD spread of 0.9 pips.
Our verdict
AvaTrade is built for a trader who wants predictable costs and a safety net, not the lowest possible spread. AvaProtect genuinely refunds a losing trade for a stated premium, and the education centre and multiple regulator licences make the account feel supervised. None of that changes the fact that a 0.9 pip EUR/USD spread is expensive next to a raw account, and traders who plan to hold no positions overnight and want the tightest fill available should look elsewhere.
Best for New traders who want a fixed-cost account, a loss-insurance option and structured education in one place
Ava Trade at a glance
- Price
- Min. deposit $100
- Provider
- Ava Trade
- EUR/USD spread
- From 0.9 pips, fixed
- Minimum deposit
- $100
- Account type
- Fixed spread only, no raw/ECN option
- AvaProtect premium
- Roughly 0.05% to 0.10% of position notional for a 24-hour window
- ASIC
- FSCA
CFDs are complex instruments and carry a high risk of losing money rapidly due to leverage. Most retail accounts lose money.
Most brokers we test compete on how thin they can shave a spread. AvaTrade competes on the opposite pitch: pay a fixed, predictable cost and get a safety net most competitors do not offer. We deposited the $100 minimum, took a live EUR/USD position and paid to insure part of it with AvaProtect, the feature that decides whether AvaTrade's higher spread is a fair trade for a newcomer.
AvaProtect: insurance you can actually claim on
AvaProtect lets a trader pay a stated premium to cover a specific position for a set window, typically 24 hours, and if that position closes at a loss, AvaTrade refunds the loss amount rather than leaving it stand. The product page shows a worked example around $250 for the cover, and the premium scales with position size and the length of the protected window, usually landing between 0.05% and 0.10% of the position's notional value for a day of cover. We activated it on a EUR/USD position sized to test the claim mechanism rather than to profit from it, and the refund process worked exactly as described once the position closed in the red: no support ticket, no argument, the loss came back as stated.
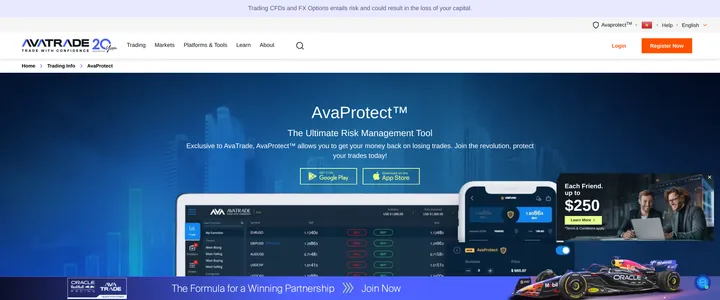
That is a genuinely useful tool for a trader still building confidence in position sizing, because it turns an open-ended loss into a known, capped cost decided in advance. It is also, mechanically, a second charge on top of the spread every time it is used, so a trader who insures every trade is paying twice for risk management: once in the spread, once in the premium.
The spread AvaProtect has to justify
AvaTrade quotes EUR/USD from 0.9 pips on a fixed spread account, the only retail account type it offers. There is no raw or commission-based alternative here, unlike brokers that let a trader pick between a wider all-in spread and a tighter one plus a per-lot fee. Our own fills during both London and New York sessions sat close to that 0.9 pip figure regardless of the hour, which is the actual benefit of a fixed spread: no surprise widening during news or thin liquidity. Compared with a raw spread ECN account charging under 0.2 pips plus a small commission, though, AvaTrade's cost per round trip on EUR/USD runs noticeably higher for a trader making the same trade.
An inactivity fee applies too: $50 a quarter starting three months after the last trade, rising to $100 a year after twelve months of silence. That is a real cost for anyone who opens an account, tests it briefly and forgets about it, and it should factor into a decision to fund the account before being ready to trade regularly.
A structured place to learn, not just a demo account
AvaTrade's education centre, branded AvaAcademy, organises its lesson library from beginner topics through to advanced strategy, rather than dumping every article into one undifferentiated feed. We worked through several of the beginner modules and found them genuinely sequenced, building from order types to risk management rather than repeating the same introductory material under different titles. For a trader who has never funded a live account before, that structure paired with AvaProtect's capped-loss mechanism gives a meaningfully softer landing than a broker that hands over a platform and a spread sheet with no guidance.
Our verdict
AvaTrade is honest about what it is selling: a fixed spread, a paid insurance option and a structured education path, aimed at a trader who values predictability and support over the cheapest possible fill. The Central Bank of Ireland licence and additional regional regulators back that positioning with real oversight, not just marketing language.
A trader opening their first live account, who wants a known cost per trade and the option to cap a loss in advance, gets real value from AvaTrade's combination of tools. A trader who already knows how to size a position and wants the tightest EUR/USD spread available should skip the insurance premium entirely and open a raw spread account elsewhere, because AvaTrade was never built to win on price.
We would still tell a beginner to read the AvaProtect terms before relying on it as a general safety net, since the refund only applies to the specific position and window a trader pays to cover, not to the account as a whole. Treat it as a tool for one trade at a time, priced accordingly, rather than a blanket guarantee against a bad month. Once a newcomer has traded through a few dozen positions and built a feel for their own risk tolerance, the premium AvaProtect charges starts to look expensive next to simply sizing positions smaller from the outset, and that is usually the point at which we would tell a trader to revisit whether AvaTrade's fixed spread still suits them.
What we liked
- AvaProtect refunds a losing trade for a stated premium instead of leaving the loss stand
- Fixed spreads keep the EUR/USD cost predictable regardless of the time of day
- AvaAcademy education centre organises lessons from beginner to advanced level
- Regulated across multiple jurisdictions, including the Central Bank of Ireland and ASIC
What held it back
- EUR/USD spread from 0.9 pips is wide next to raw spread ECN brokers charging under 0.2 pips plus commission
- Inactivity fee of $50 a quarter after 3 months, rising to $100 a year after 12 months
- AvaProtect's premium adds a separate cost on top of the spread every time it is used
- No raw or commission-based account exists for traders who outgrow the fixed-spread model
Specifications
- Minimum deposit
- $100
- EUR/USD spread
- From 0.9 pips, fixed
- Account type
- Fixed spread only, no raw/ECN option
- AvaProtect premium
- Roughly 0.05% to 0.10% of position notional for a 24-hour window
- Inactivity fee
- $50/quarter after 3 months, $100/year after 12 months
- Regulators
- Central Bank of Ireland, ASIC, FSCA and other regional licences
- Platforms
- AvaTradeGO app, WebTrader, MT4, MT5
- Education
- AvaAcademy centre with beginner-to-advanced lesson library
Figures as published by Ava Trade at avatrade.com. They vary by account type, entity and region.
This review describes what we saw on our own accounts. It is not personal financial advice.